When I think about funding a company, I do not see one universal answer. I see a tradeoff between speed, ownership, control, risk, and timing. Venture capital can be a powerful engine for a business that needs to grow very fast, but I have also seen many founders take VC money too early, give away too much equity, and then feel trapped by expectations that no longer match their business. That is where revenue-based financing can become a smarter option.
I pay close attention to this choice because it is not only about raising money. It is about choosing a financing structure that fits the actual shape of a business. If a company already has predictable sales, healthy margins, and room to grow without needing a huge cash burn, revenue-based financing can preserve ownership while still providing fuel for expansion. In my view, that matters more than chasing prestige capital just because it looks impressive on paper.
Why revenue-based financing can fit better than venture capital
I usually see revenue-based financing work especially well when a company already generates recurring or repeatable revenue. Think about SaaS, e-commerce, digital products, subscription brands, or service businesses with strong unit economics. In those cases, a founder may not need a giant VC round to chase a long, uncertain path to scale. Instead, a company may simply need capital to accelerate marketing, inventory, hiring, or acquisition channels that already work.
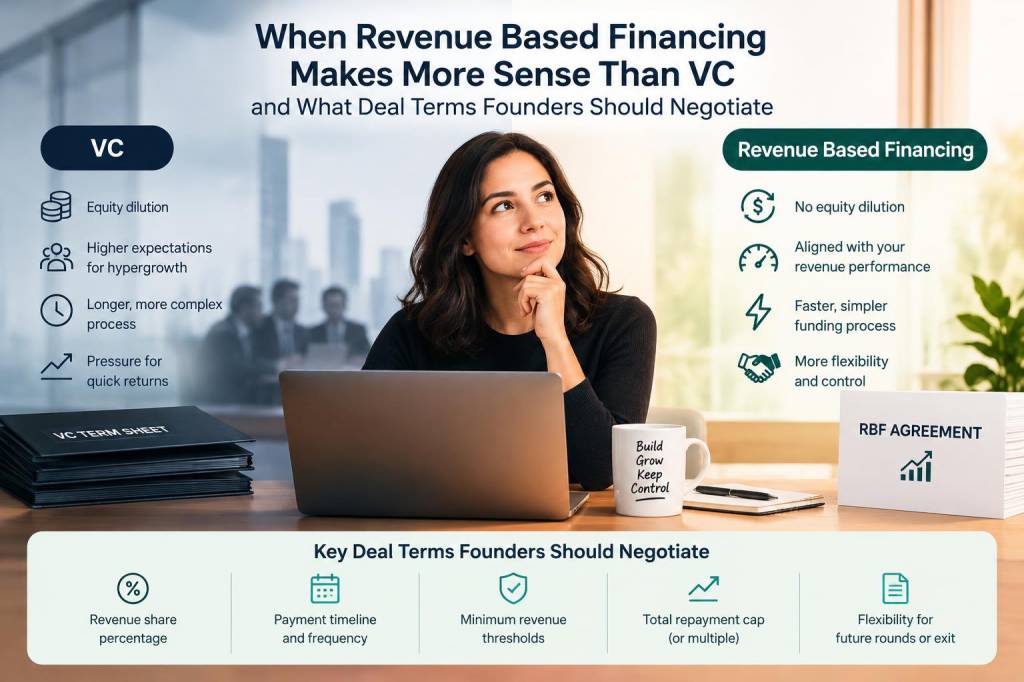
The biggest difference is simple: venture capital is built around equity exchange and high growth expectations, while revenue-based financing is built around a repayment structure tied to future sales. With VC, investors usually want a meaningful ownership stake and often expect outsized returns through a large exit. With revenue-based financing, capital providers are usually repaid through a percentage of revenue until a fixed amount is paid back.
That structure can feel much more aligned if I want to keep control of the business and avoid constant pressure to hit hypergrowth milestones. I also like that revenue-based financing can be less emotionally heavy than VC. I do not have to spend as much time adjusting my strategy to fit investor narratives, board dynamics, or a future acquisition story that may not be relevant to my business.
Another reason I find it appealing is dilution avoidance. Every founder knows that equity is precious. If a business can grow with non-dilutive capital, I think it deserves serious consideration. In many cases, preserving ownership early can create far more value later than accepting a large valuation today and losing meaningful upside.
Situations where I would lean toward revenue-based financing
There are a few situations where I would naturally lean in this direction:
- A business already has steady monthly revenue and clear demand.
- Gross margins are strong enough to support repayment from cash flow.
- The company does not need a long runway for research-heavy development.
- Founders want to preserve control and limit dilution.
- Growth can be funded through near-term sales rather than speculative future value.
I also think revenue-based financing becomes more attractive when a founder does not want to lock the company into a high-pressure venture path. Not every business needs to become a venture-scale company. In fact, many excellent companies are built with disciplined growth, strong profitability, and a preference for independence.
I have seen founders underestimate the cost of VC beyond equity. Once a venture round is closed, expectations change. Growth targets become more aggressive. Reporting becomes more formal. Strategic flexibility can narrow. That is not necessarily a bad thing if the company is truly built for that path, but it can be a poor fit for businesses that want steady control and practical scaling.
When venture capital still makes more sense
I would not pretend revenue-based financing is always superior. It is not. If a company needs a very large amount of capital upfront and has the potential to dominate a category quickly, venture capital may still be the right choice. That is especially true for businesses that require heavy product development, network effects, long customer acquisition cycles, or substantial market capture before profitability is realistic.
I also think VC can make sense when a startup needs strategic support beyond money. Some investors bring deep industry expertise, access to talent, connections to later-stage capital, and help with scaling operations. For the right founder and the right company, that can be valuable.
Still, I believe founders should not assume VC is automatically superior. If the business can grow efficiently without surrendering too much ownership, revenue-based financing may create a healthier long-term outcome.
Deal terms I would negotiate carefully
Once I decide that revenue-based financing is worth exploring, I focus on the terms. This is where a founder can either protect the business or create future stress. I never look only at the headline amount raised. I look at repayment mechanics, total cost, flexibility, and what happens if revenue rises slower than expected.
Revenue share percentage is one of the first terms I want to understand. A small percentage may sound harmless, but if it is too high, it can squeeze working capital and slow growth. I want a percentage that allows repayment without starving the business.
Repayment cap matters just as much. Many deals require repayment of a multiple of the original investment. I want to know the exact cap, because that determines the true cost of capital. A deal that looks attractive upfront can become expensive if the multiple is too high.
Payment duration is another term I review carefully. If revenue grows more slowly than projected, the repayment period can stretch longer than expected. I want to understand whether there is a fixed term, a flexible term, or any mechanisms that adjust if performance changes.
Revenue definition is extremely important. This is one of the areas where founders can get caught off guard. I want the agreement to define exactly which revenue counts, whether taxes are excluded, whether refunds are netted out, and whether certain channel revenues are included or excluded. A vague definition creates future disputes.
Prepayment rights are something I always want on my side. If the business performs better than expected, I want the option to repay early without punitive penalties. Flexibility is one of the main advantages of this financing model, and I would not want to lose that.
Financial covenants can also matter. Some agreements include minimum performance thresholds, reporting obligations, or restrictions on additional debt. I read these carefully because they can limit strategic choices later.
Default terms deserve close attention too. I want to know exactly what happens if revenue falls sharply, if there is a temporary reporting error, or if the company misses a payment. I do not like hidden traps in any financing agreement.
Negotiation points I would push for
When I negotiate a revenue-based financing deal, I focus on a few practical goals: preserve flexibility, reduce downside risk, and protect upside.
- I would push for a lower revenue share if the business has strong growth potential.
- I would try to cap the total repayment multiple at a reasonable level.
- I would ask for a clear and narrow definition of revenue.
- I would request the right to prepay without penalties.
- I would avoid terms that create operational burden or excessive reporting complexity.
- I would ask for room to take future debt or equity if needed, without restrictive approval rights.
I also think founders should negotiate based on proof, not hype. If the business has strong retention, rising average order value, efficient acquisition costs, or reliable recurring revenue, that creates leverage. I would use that leverage to argue that the company deserves fairer pricing and more founder-friendly terms.
Here is a simple comparison I find useful when deciding between revenue-based financing and VC:
| Factor | Revenue-Based Financing | Venture Capital |
|---|---|---|
| Ownership impact | No equity dilution | Equity dilution |
| Repayment structure | Percentage of revenue | No repayment, but ownership cost |
| Control | Founder keeps more control | Investors may influence strategy |
| Growth expectation | Measured, cash-flow-driven growth | High-growth, scale-at-speed model |
| Best fit | Predictable revenue and strong margins | Large, fast-scaling opportunity |
Questions I ask before signing anything
Before I would sign a deal, I ask myself a few blunt questions. Will this capital genuinely increase growth, or will it merely buy time? Can the business absorb repayments without creating stress? Is the business model strong enough that I do not need to surrender equity right now? If growth slows for a quarter, will this financing still be manageable?
I also ask whether the financing matches my long-term vision. If I want to build a durable, independent company, I may value ownership more than a headline valuation. If I want to dominate a market quickly and I know that outside support will accelerate that mission, VC may still be the better fit. The point is not to choose the “smartest” financing in abstract terms. The point is to choose the one that fits my company’s reality.
One thing I have learned is that founders often focus too much on raising money and not enough on preserving optionality. A thoughtful financing structure should expand options, not narrow them. Revenue-based financing can do that when the business has enough traction to support it and the terms are negotiated with discipline.
For founders evaluating both paths, I would treat the decision as a strategic question, not a status question. The right capital is not always the most famous capital. Sometimes it is the capital that lets a business grow on its own terms, without unnecessary dilution, without pressure to become something it is not, and without sacrificing future flexibility for short-term excitement.