When I speak with early-stage founders, one subject comes up again and again: equity feels simple at first, until people start leaving, roles change, or a company grows faster than anyone expected. A founder-friendly vesting schedule is not just a legal formality. In my view, it is one of the clearest ways to protect trust before there is any reason to doubt it. I have seen strong teams weaken because they treated founder ownership as a handshake agreement instead of a structure that could survive pressure, change, and disagreement.
What I want to share here is not legal advice, but a practical way to think about vesting from a founder’s point of view. If I were setting up a new company today, I would want a vesting schedule that feels fair, transparent, and durable. It should reward commitment, reduce resentment, and make it much easier to handle hard conversations before they become painful disputes.
Why vesting matters from day one
In early-stage startups, founders often take on huge risk before there is meaningful revenue, product-market fit, or outside investment. Because of that, people sometimes assume every cofounder should simply own an equal share from the start. I understand that instinct. It feels generous and aligned with the spirit of partnership. Yet I have learned that equal ownership without vesting can create serious problems if one founder leaves after a few months while still keeping a large stake.
A vesting schedule helps separate promise from performance. It says, in effect, that equity is earned over time, not handed over all at once. For early-stage founders, that matters because circumstances change. Someone may realize the role is not a fit. Someone may relocate. Someone may become less involved after a product launch or a funding round. Vesting gives the company a fair mechanism to reflect those changes without turning every departure into a fight.
I also think vesting has a psychological benefit. It encourages founders to stay engaged, communicate openly, and think long term. When everyone knows ownership is tied to ongoing contribution, it becomes easier to focus on building together rather than quietly worrying about who is contributing what.
What I would expect in a founder-friendly structure
A founder-friendly vesting schedule should protect both the company and the people who create it. For me, that means it should feel balanced, not punitive. It should not assume bad faith, but it should be prepared for reality. I would want several elements in place so the arrangement is clear from the beginning.
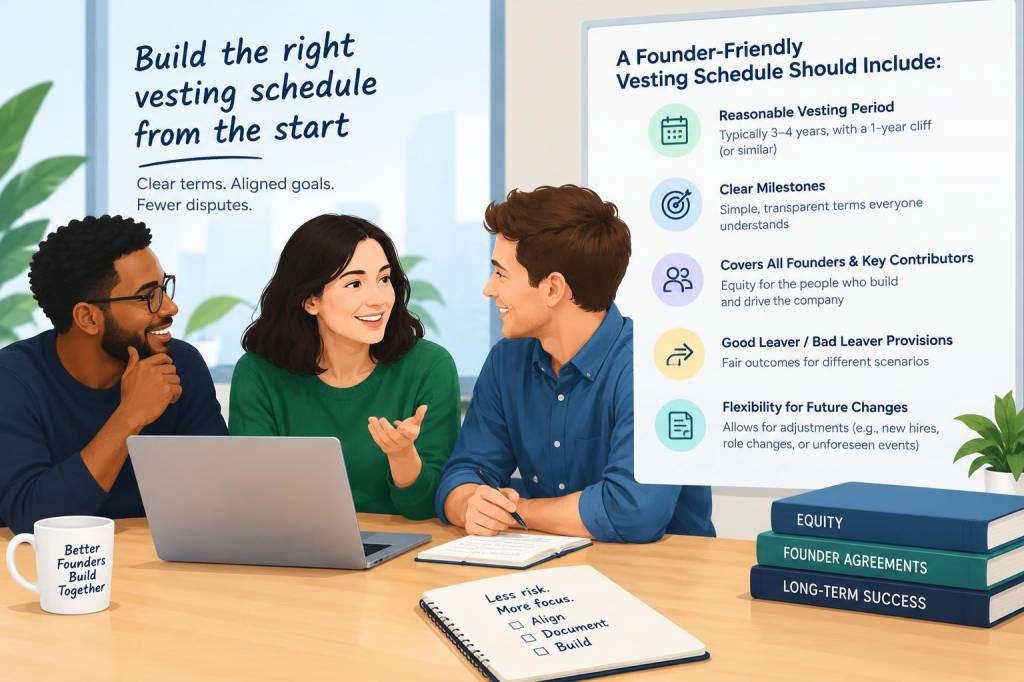
- A standard vesting period that is long enough to reward commitment, usually four years in startup practice.
- A cliff period so that very early departures do not receive a disproportionate reward for limited involvement.
- Monthly or quarterly vesting after the cliff so equity is earned steadily over time.
- Clear role definitions so that founders know what contribution is expected from each person.
- Acceleration language for unusual events such as acquisition or control change.
- Repurchase or buyback rights so unvested shares can be reclaimed if a founder exits early.
- Deadlock and dispute procedures so conflicts have a path to resolution before they damage the business.
For me, the phrase founder-friendly does not mean “loose” or “informal.” It means the structure recognizes that founders are humans, not machines. It should be protective without being aggressive, and it should avoid language that makes honest people feel trapped.
Cliff periods and why they matter so much
The cliff is usually the first issue I look at because it can create frustration if it is misunderstood. A cliff is the initial waiting period before vesting begins. If a founder leaves before that period ends, no shares vest. After the cliff, vesting usually continues gradually.
I have found that a cliff is useful because it filters out short-lived involvement. Startups are full of optimism in the early weeks, but not every partnership survives the reality of building under pressure. Without a cliff, a founder who leaves very early might still retain a meaningful stake. That can create resentment among the people who stayed, especially if the remaining team has to rebuild momentum from scratch.
At the same time, I believe the cliff should be explained with absolute clarity from the beginning. Nothing creates conflict faster than one founder assuming the cliff is symbolic while another treats it as rigid. I would always want the team to discuss what happens if someone contributes heavily during the first months, then steps away before the cliff ends. Those edge cases are where many disputes begin.
How much equity should vest at a time
Another detail that matters is the vesting cadence. Some structures vest monthly after the cliff, while others use quarterly vesting. I personally prefer a schedule that feels smooth and easy to track. Monthly vesting tends to reduce tension because it matches work more closely and makes it simpler to account for partial contributions.
Quarterly vesting can still work, especially if the founders want administrative simplicity. What matters most is that the mechanism is easy to understand and tied to a real pattern of commitment. I would avoid any setup that feels mysterious or overly clever. The more complicated the math, the more likely someone will later claim they understood it differently.
I also think it helps to define vesting in relation to active service. If a founder changes roles, reduces involvement, or takes on a different responsibility, the schedule should state whether vesting continues unchanged or requires adjustment. That conversation may feel uncomfortable at the outset, but it is much easier to handle before there is money, visibility, or investor pressure involved.
Acceleration language should be specific, not vague
Acceleration is one of those terms that sounds technical but becomes very emotional when a company is sold or restructured. In plain language, acceleration determines whether unvested equity becomes vested faster under certain events. I have seen founders assume acceleration will protect them in any acquisition, only to discover that the contract was narrower than expected.
If I were negotiating a founder-friendly agreement, I would want the acceleration terms to be very specific. For example, the agreement should say whether acceleration happens on a change of control, whether it is partial or full, and whether it depends on a founder being terminated without cause after the transaction. These distinctions matter a great deal.
One reason I care about this is that acquisitions are rarely simple. A buyer may want the founding team to stay on for a transition period. A founder may want freedom to leave after a sale without losing value that was earned through years of effort. Clear acceleration terms reduce the chance that both sides later feel misled.
What I would want in the paperwork
Good intentions are not enough. A vesting schedule needs documentation that is easy to read and hard to misunderstand. I would want the agreement to spell out each founder’s starting equity, vesting start date, cliff date, vesting frequency, and what happens if a founder resigns, is removed, becomes inactive, or dies. None of these topics are pleasant, but each one is relevant.
I would also want the agreement to state whether the company has the right to repurchase unvested shares, on what terms, and at what price. This is one of the most practical protections in the entire structure. If a founder leaves after a short period, the company should not be left with a cap table that rewards unfinished work indefinitely.
Here is a simple comparison of elements I would consider essential:
| Element | Purpose | What I would look for |
|---|---|---|
| Vesting period | Rewards long-term commitment | Long enough to reflect real contribution, usually several years |
| Cliff | Prevents very early exits from earning equity too soon | Clear start and end dates |
| Vesting cadence | Defines when equity is earned | Simple monthly or quarterly schedule |
| Acceleration | Protects founders in major transactions | Specific triggers and outcomes |
| Repurchase rights | Lets the company reclaim unvested shares | Fair process and clear pricing |
What founders often forget to discuss
In my experience, the hardest disputes are rarely about the headline terms. They are about assumptions that were never written down. Founders often forget to discuss what happens if one person works full time while another stays part time. They may not address what happens if someone is on leave, shifts into an advisory role, or spends months on fundraising instead of product work. These are not rare scenarios. They are normal startup life.
I also think many founders forget to discuss emotional fairness. A schedule can be legally precise and still feel unfair if the team never talked about expectations. If one cofounder believes they are carrying the company while another believes they are contributing in less visible ways, resentment will build. A good vesting structure does not replace conversation. It supports it.
When I talk about fairness, I mean fairness in contribution, risk, and timing. The founder who joined first may deserve recognition for initiating the company, but the founder who stayed through difficult months may deserve equal recognition for persistence. Vesting gives everyone a common framework for that conversation.
How I would handle vesting discussions with cofounders
If I were sitting with a new founding team, I would ask each person to answer a few direct questions in writing: What are you committing to? How much time will you spend? What skills are you bringing? What happens if your circumstances change? Those answers are not just useful for equity. They build trust.
I would also encourage founders to talk about worst-case scenarios before they happen. That includes voluntary departure, underperformance, illness, role changes, and acquisition. These conversations can feel awkward, but they are often a sign of maturity rather than distrust. A team that can discuss hard topics early is usually better prepared to survive difficult moments later.
And if investors are likely to join later, I would make sure the vesting structure is understandable to them as well. Investors often want to know that the founding team is locked in and that the company will not be burdened by a messy cap table. A clean founder vesting setup can actually strengthen fundraising conversations because it signals discipline and foresight.
The questions I always ask before signing anything
- Does every founder understand when vesting starts and ends?
- Is the cliff explained in plain language?
- What happens if someone leaves before the cliff?
- What happens if someone changes roles but stays involved?
- Is acceleration defined clearly enough to avoid future argument?
- Can the company repurchase unvested shares without confusion?
- Have all founders accepted the same logic for equity earning?
When I answer those questions honestly, I usually find the weak spots in the agreement before they become expensive problems. That is why I believe a founder-friendly vesting schedule is not just about equity. It is about preserving relationships, protecting momentum, and making sure the company’s ownership structure reflects reality rather than optimism.
In startups, reality changes quickly. A vesting schedule that is thoughtful from day one gives founders a shared framework for change, and that, in my experience, is one of the most valuable forms of protection a young company can have.